Horizon B2B Trading is dedicated to connecting the global marketplace by sourcing, manufacturing and distributing high-quality products from all corners of the world. Our mission is to facilitate seamless trade, fostering mutual prosperity and sustainable growth for businesses worldwide.
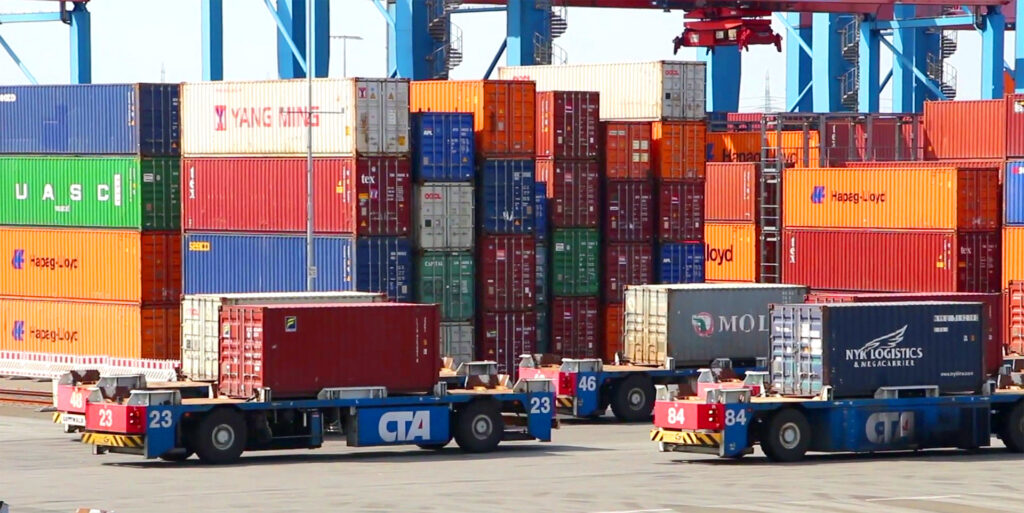
Importations
Looking to import 20′, 40′ or 40’HC containers?
Struggling with increasing shipping prices?
Want a complete one stop service to handle all shipping aspects?
Get a quote today!
We work very closely with some of the biggest names in the industry and can offer very attractive shipping rates.
Shipping Quote
China and SE Asia Shipping News – November 2026
Price Trends
Asia–Europe spot rates stabilised through late October into early November after the post-peak and Golden Week softness, with modest firming supported by blank sailings, residual congestion, and carriers’ FAK attempts ahead of 2027 contract tendering. Levels remain well above early-2026 and year-ago benchmarks but far below July peaks.
Latest Drewry World Container Index (WCI) readings (around 29 October / early November): Composite index fell 3% to ~$4,429 per 40ft container (reversing two weeks of gains, driven mainly by Transpacific declines). Shanghai–Rotterdam rose 1% to approximately $3,686/FEU. Shanghai–Genoa held steady at around $4,151/FEU.
Freightos Baltic Index (FBX) readings in late October/early November showed Asia–N. Europe (FBX11) in the ~$3,500–$3,600/FEU range (e.g., recent prints around $3,551–$3,595, up modestly in some weeks), while Asia–Mediterranean eased or held in the mid-to-high $3,500s to low $4,000s in places (with some earlier rebounds to ~$4,250). Global FBX has hovered near ~$3,500 recently.
A realistic working range for China–UK/Northern Europe in November is roughly $3,400–$4,200 per FEU (with UK ports like Felixstowe/Southampton tracking the Northern Europe average, sometimes with modest premiums). Carriers have announced higher FAK rates for early-to-mid November (e.g., MSC targeting ~$4,500 on Asia–N. Europe and higher on Med; CMA CGM aiming for elevated Med levels), plus further attempts mid-month. Success is uncertain amid soft demand and added Suez capacity; analysts (including Drewry and Linerlytica) expect limited stickiness, with rates more likely to remain broadly stable or face modest downward pressure as discounting appears in the spot market.
Route Changes
Two key factors continue to shape Asia–Europe routing:
Strait of Hormuz: Traffic remains heavily constrained and far below pre-crisis norms (AIS-visible commercial crossings often in the single digits to low teens per day recently versus ~70–100+ previously; ~10% or less of normal in many recent assessments). The disruption is now past ~250 days. Risk, insurance costs (still multiples of peacetime levels), and operational uncertainty persist, with limited commercial throughput. Some vessels use alternative arrangements or dark AIS.
Red Sea / Suez Canal: Progressive returns have accelerated and are the dominant constructive development. Major carriers (MSC, Maersk/Gemini with Hapag-Lloyd, CMA CGM, Ocean Alliance including Cosco/OOCL, and now Premier Alliance partners ONE/HMM/Yang Ming) have restored or are restoring the majority of Asia–Europe and Asia–Mediterranean services. Alphaliner and others estimate ~63% of Far East–Europe capacity (around 5.5m TEU of ~8.7m) is now assigned to Suez/Red Sea loops (higher share ~70% on Med routes, ~58% on Northern Europe). Large/megamax vessels are returning in greater numbers; weekly containership transits have hit recent highs. Full or near-full normalisation by Q1 2027 is widely expected (leaving mainly Zim and limited holdouts on the Cape for contingency reasons). Broader normalisation by end-2026 remains plausible for most capacity.
Transit times for China–UK cargo are therefore improving for the growing share of Suez-restored services (shorter voyages), while Cape routing remains in use for a minority of sailings (typically still 40–50+ days). Vessel bunching from mixed routings can still affect European arrivals.
Shipping Carrier Activities
Blank sailings remain in use on Asia–Europe but at relatively modest levels overall (e.g., four announced for the week after late-October assessments, down from eight previously in some weeks; broader East-West cancellation rates often in the 5–8% range). These help manage capacity amid soft demand and the capacity release from shorter Suez voyages, though overall blanking has not been as aggressive as in some prior soft periods. Carriers are balancing this with FAK pushes and selective capacity management.
Progressive Suez returns by MSC, Maersk/Gemini, CMA CGM, Ocean Alliance, Premier Alliance and others remain the dominant operational theme, implemented service-by-service with contingency options retained. Equipment and space availability are generally more manageable than at peak, supported by residual blanks, though residual congestion effects (Shanghai waiting times have improved from earlier highs but can still fluctuate with weather/typhoons; Northern Europe hubs face risks of arrival bunching and occasional labour or inland issues) and schedule reliability challenges persist.
Possible Risks to Rates
Geopolitical: Any deterioration around Hormuz or a fresh Red Sea/Houthi-related incident could reverse Suez progress and reinstate higher risk premiums/insurance costs.
Demand: Soft European import volumes and post-peak/seasonal weakness would add downward pressure. Stronger-than-expected restocking or tender-related activity could help stabilise or support levels.
Capacity release: Continued and expanding Suez returns increase effective capacity on Asia–Europe, which tends to weigh on rates unless carriers respond with more aggressive blank sailings.
Operational: Residual port congestion (especially Shanghai and some Northern Europe hubs), potential arrival surges from mixed Cape/Suez routing, fuel costs linked to Middle East disruption, and schedule reliability remain factors. US trade policy developments can also influence broader East-West dynamics.
Rates are expected to remain relatively stable in the near term with downside risks from capacity and demand, though carrier capacity management and any demand surprises could limit further falls.
We have the knowledge!
Choose Horizon B2B Trading for YOUR FCL shipping needs!
Get a shipping quote from us – just use the form above!
Kitchens and Bathrooms
With a wide range of styles and choices, we offer a full catalogue of bespoke kitchens and bathrooms for commercial applications.
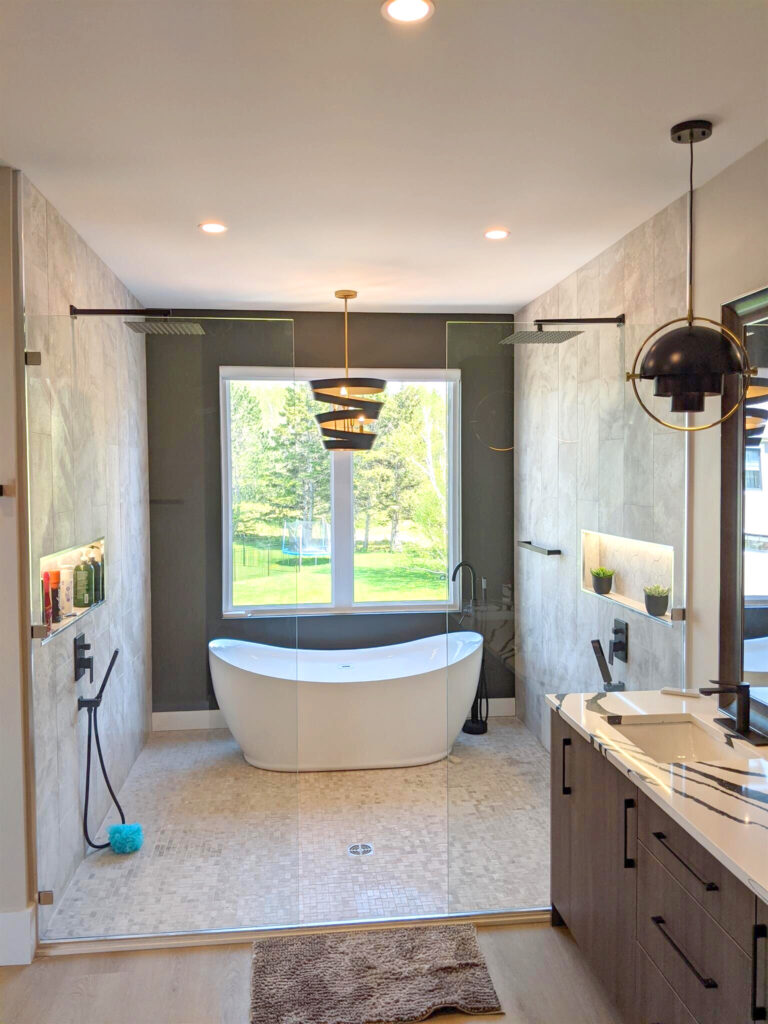
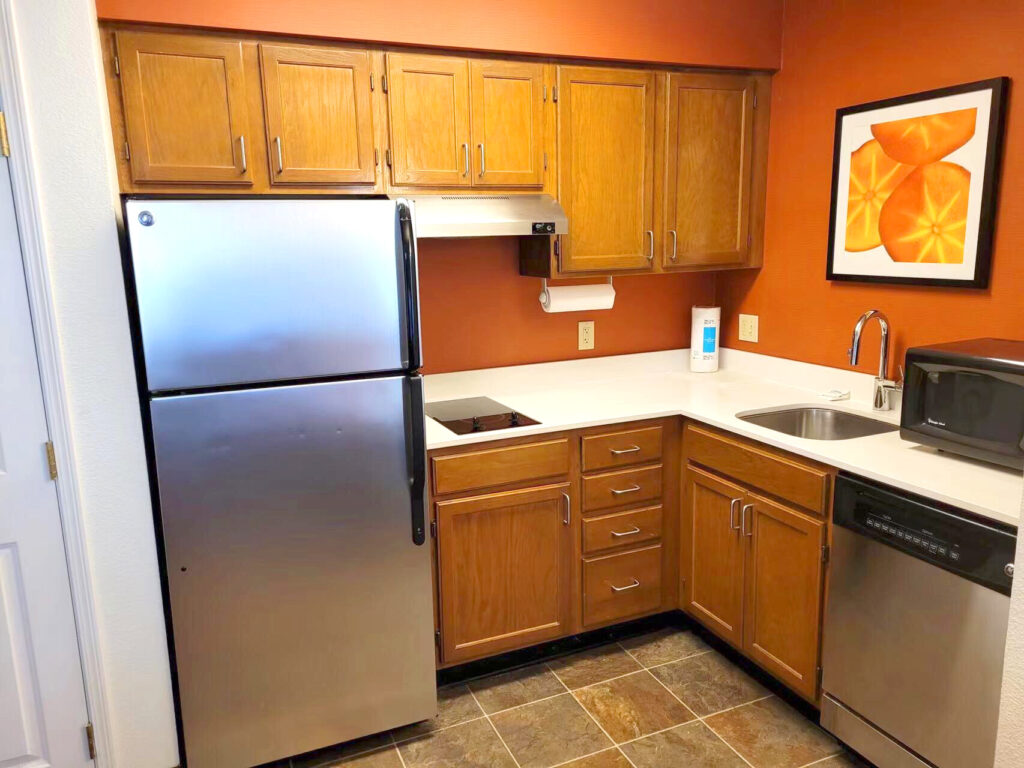
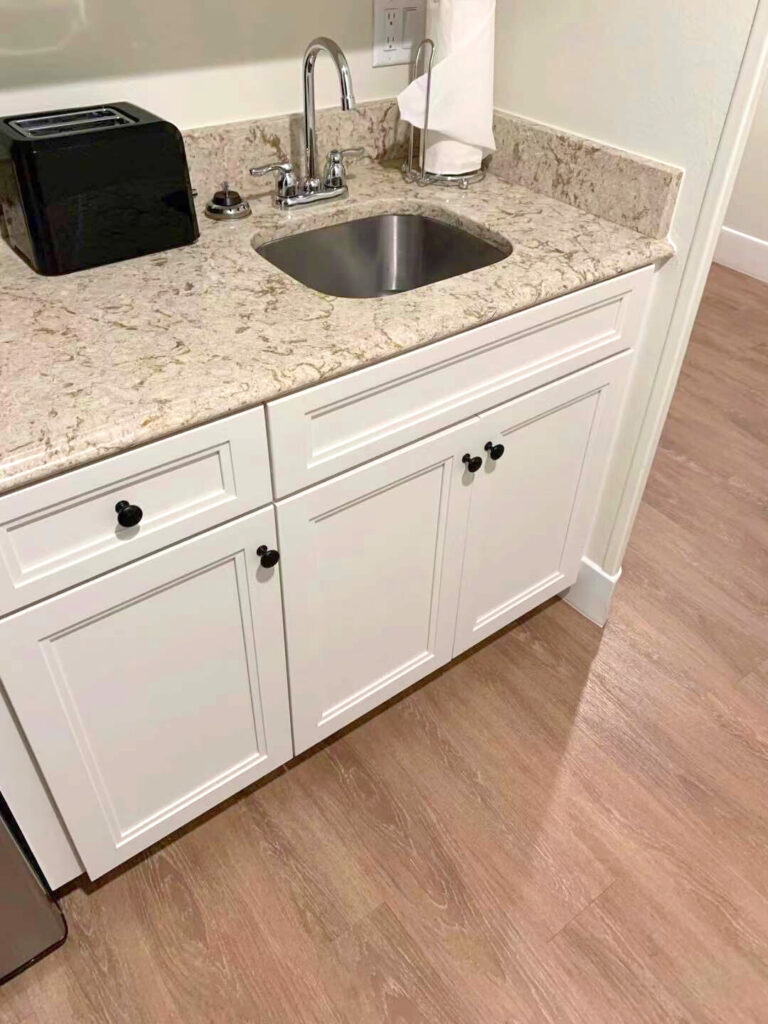
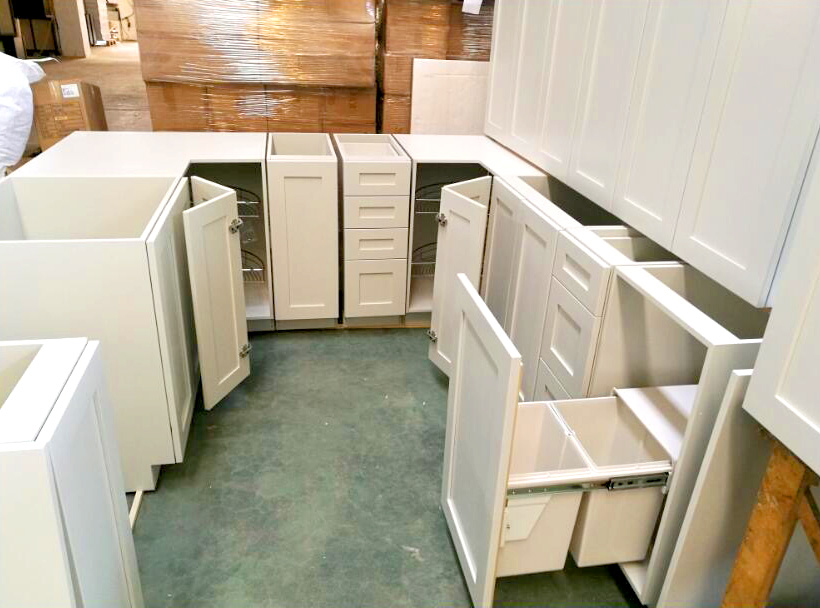
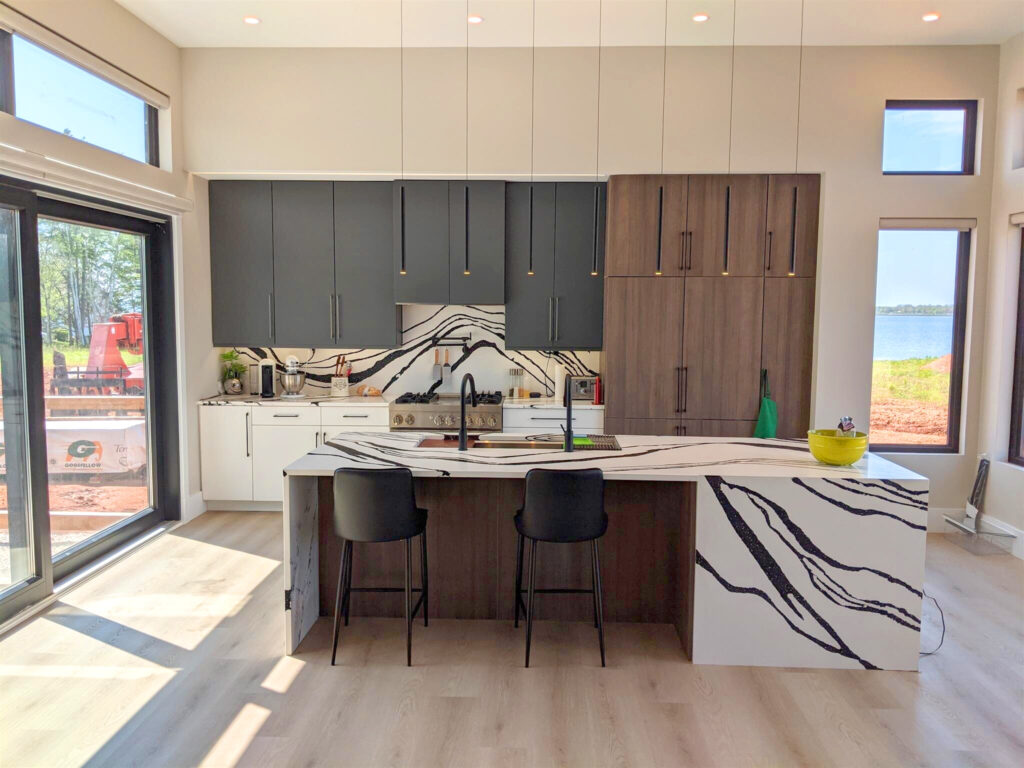
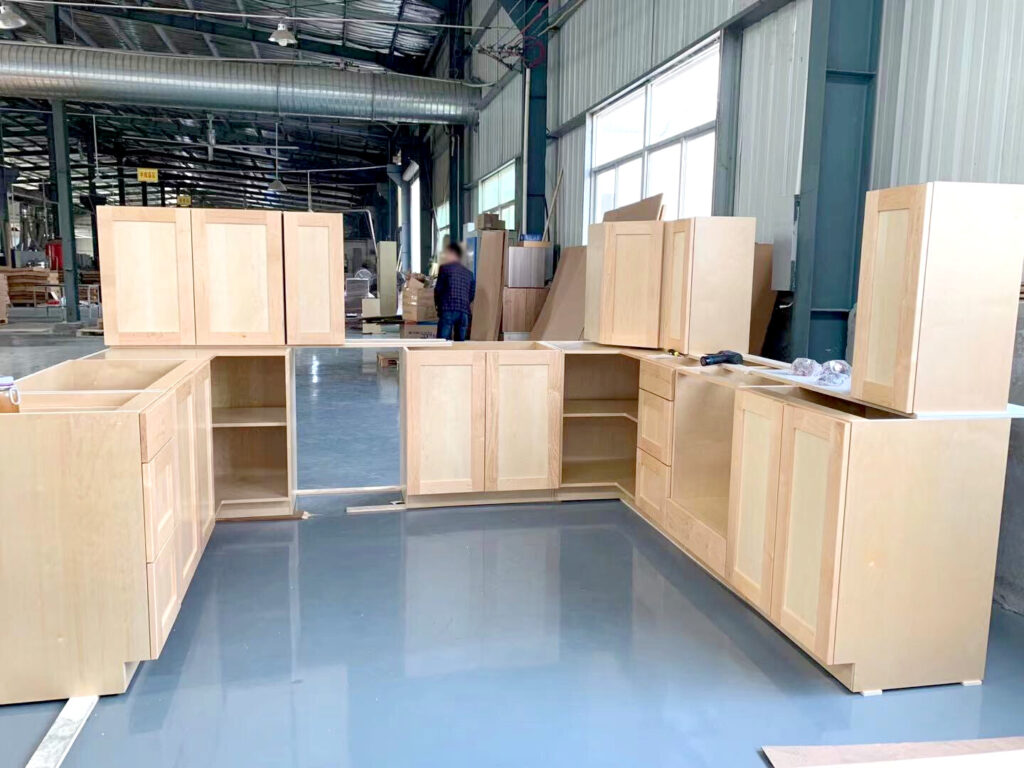
Over 20 years in manufacturing in a variety of sectors provides Horizon B2B Trading with the experience, knowledge and track record to deliver high quality, high volume solutions to many commercial trades.
If you’re looking for tailored programmes to fit your custom specifications and volumes, then enquire today and let us help. We specialise in large volume sourcing, manufacturing and distribution.
“Making B2B as easy as ABC“
CPH, CA
Contact us
+44 (0)1423 506669
12 Station Parade
Harrogate
North Yorkshire
HG1 1UE